

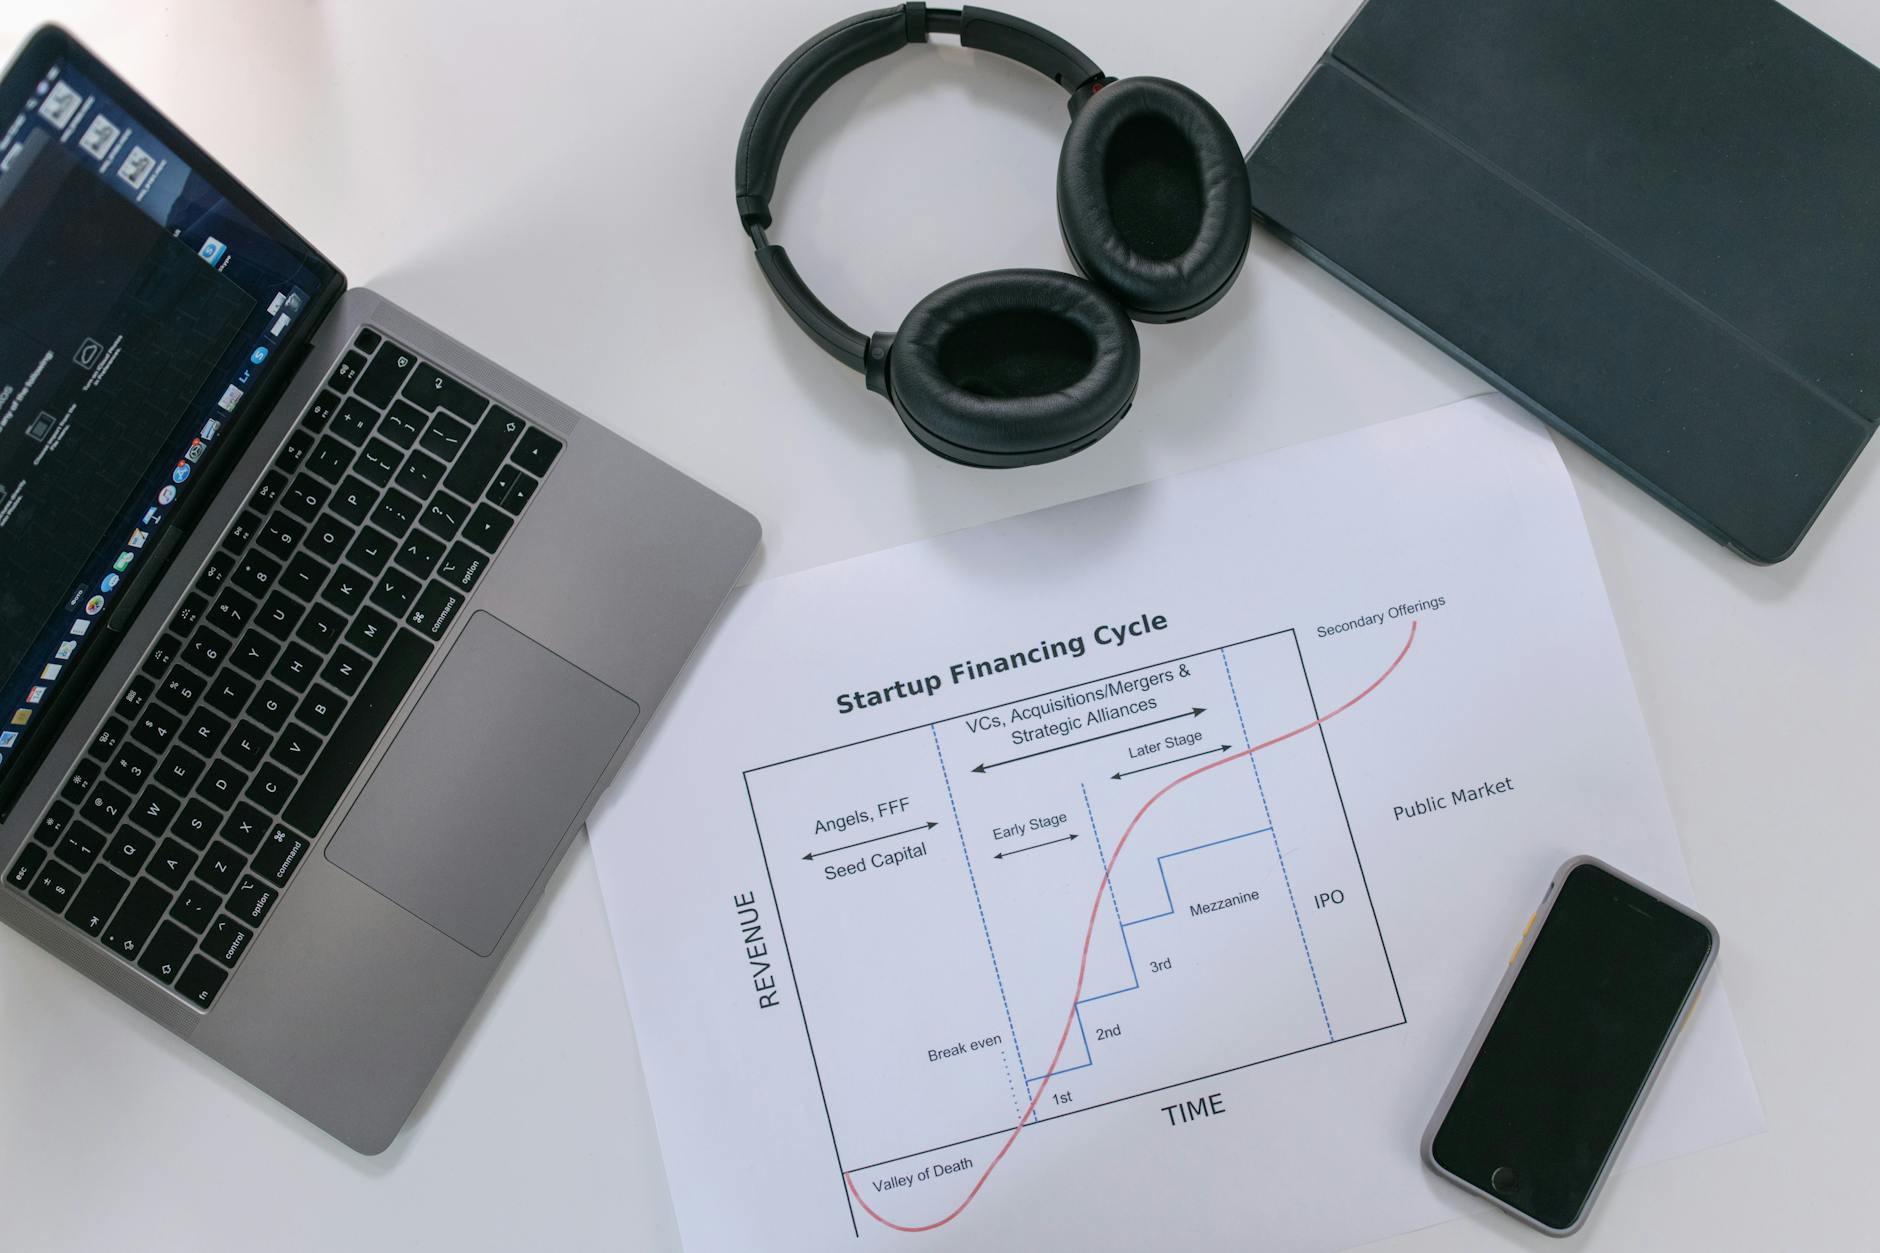
Modern workspace with laptop representing capital raising and startup financing

Issuing a convertible note to raise capital

Raise capital now without setting a price on your business yet.

An investor is ready and you are not ready to name a price. A convertible note is the instrument that resolves that: money in now, equity later, at a valuation set by a round you have not run yet. We draft the note, negotiate the discount, cap and maturity with your investor, and make sure the conversion mechanics say what everyone thinks they say. You raise the capital without deciding today what your company is worth.

Capital now, valuation later

The money lands while the price of your equity stays open, which is the whole point of a note.

Conversion terms you agreed

The discount, the cap and the trigger are written down before the money moves, rather than argued about at the round.

A note investors recognise

The document reads the way an incoming investor expects, so your next round isn't slowed down explaining it.

What is a convertible note and how does it work?

A convertible note is short-term debt that turns into equity instead of being repaid. The investor lends the money now, and when a priced funding round happens the loan converts into shares, usually at a discount to what the new investors pay and subject to a ceiling on the valuation used. That ceiling is the valuation cap, the discount is the reward for coming in early, and the maturity date is the backstop if no round arrives. Capital raising is regulated under the Corporations Act 2001 (Cth) (the Act), and how you offer a note decides which of its disclosure rules apply to you.

A convertible note is short-term debt that is expected to turn into equity rather than be repaid, usually when a priced round happens. A standard loan is repaid on a schedule, with interest, and leaves ownership untouched. The trade-off is that a note is cheaper on cash flow now and costs you equity later.

The cap is a ceiling on the valuation used when the note converts, so an investor who came in early is not penalised if the company has grown a great deal by the time of the round. It is usually the single term with the biggest effect on how much of the company the note ends up being worth. It is worth negotiating rather than accepting.

That depends entirely on what the note says, which is why it needs to say something. The usual options are conversion at an agreed valuation, repayment, or an extension by agreement. A note that is silent on it leaves you exposed to a repayment demand at the worst possible moment.

Often, yes. Offering a note is offering a financial product, and the Corporations Act sets out when a disclosure document is required and which exemptions are available. It usually turns on who you are offering it to and how many of them there are. We will tell you which position you are in before the offer goes out.

Want to understand your options before committing?

Before anything is drafted, it is worth knowing whether a note suits this raise at all. Tell us who the investor is, how much is on the table, and when you expect to run a priced round.

You are agreeing now what a share of your company will be worth later

You need the capital and you don’t yet have the evidence to argue a valuation you would be happy with. A note defers that argument, but only if the discount, the cap and the trigger are written down properly, and those are the terms you are least equipped to judge at the moment you are asked to sign them. The worry underneath is simple: you can’t tell whether you have given away a little or a lot until the round that converts it.

An investor is ready before the valuation is

The business is working. Someone who has been watching it wants in, and they are ready now rather than after your next milestone. You would rather not price the company at this moment, because the number you could defend today isn’t the number you think it will be worth in a year. So you are being offered money on terms that settle something you had deliberately chosen not to settle.

What's included in your convertible note service

Vague conversion terms are paid for at the next round

A note that is thin on the conversion mechanics causes no trouble on the day it is signed. It causes trouble at the round, when the discount turns out to be ambiguous about which price it discounts, or the cap is silent on whether it applies before or after the new money, and the answer is worth a meaningful slice of the company. By then your incoming lead investor is reading the note as part of their diligence, so the argument is neither private nor quick. And if the maturity date passes with no round and the document doesn’t say what happens next, the holder can be entitled to repayment at exactly the moment your cash is committed elsewhere. Each of these is a drafting question that costs almost nothing to settle now.

How we put you in control of your own raise

We start with the commercial shape: how much, from whom, and what has to happen before it converts. Then the terms get negotiated rather than accepted, because a discount and a cap are positions, not standards, and the first draft you are sent is the investor’s position. The note is drafted so the conversion arithmetic can only be read one way, the maturity outcome is stated, and the investor’s rights on a sale or a wind-up are explicit. What you end up with is a raise you understood before you signed it, and a document your next investor reads without pausing.

Three steps to capital on terms you chose

Money now, valuation later, mechanics settled.
1

Set the terms

We work through the amount, the discount, the cap and the maturity, and tell you which of them are worth pushing on.

2

Document the note

We draft the note so the conversion arithmetic and the maturity outcome can only be read one way.

3

Close the raise

We handle execution, the company records and the disclosure position, so the money is in and the paperwork matches.

Terms negotiated by people who have read the other side's draft before

Raising money is the part of running a business where founders are most often asked to decide quickly on terms they have never seen before. The investor across the table has usually done this more times than you have.

We have 2 Accredited Specialists in Business Law. We also have 2 Family Business Association accredited advisors, and we are the FBA State Partner in South Australia, which counts on a raise where the existing shareholders are a family. We are ISO 9001 accredited as well, so what happens on your file, and when you hear about it, are defined rather than assumed.

Our great lawyer guarantee

Six principles we hold to, whatever you bring us and however long it takes.

Take the time

We listen carefully to understand what you want to achieve, then step you through the advice and the documents.

Share our knowledge

We pass on as much as we can, so you can make your own informed decisions.

Stick to our knitting

We only do what we are good at, so you never pay for our learning.

Work as one team

Someone is always available to answer your question or point you the right way.

Fair pricing

A fixed or capped quote for advice and documents, so you do not carry the price risk.

It is your show

We are in it for a front row seat to witness your success, not for our egos.

Ready to raise on terms you set?

A note lets you take the money now and price the company later. Tell us what is on the table, and we will tell you what the terms are actually worth.

More on this area of law

See all articles